

News and Views
Invisible technology, hyper-local formats and experience-led environments driving ROIC. Trends 2027–2029.


Supermarket Trends 2027–2029: AI, Hyper-Local Formats, Experience & ROIC
The supermarket of 2027–2029 will not be defined by technology alone. Its competitive advantage will come from connecting AI, customer intelligence, hyper-local formats, store design, fresh-food experience and measurable commercial performance.
The six supermarket trends most likely to shape the next three years are:
- Invisible AI and predictive supermarket technology
- Hyper-local supermarket formats and localised assortments
- Experience-led supermarket design
- Fresh food, food-to-go and hospitality as growth platforms
- Phygital retail and connected customer journeys
- ROIC-led supermarket investment and productivity
The strategic shift is from adding technology to existing stores towards using data and customer intelligence to determine what each store should be, how it should operate and what return it should generate.
Shopper intelligence → AI → format strategy → brand → store design → experience → productivity → ROIC
That is the emerging supermarket model for 2027–2029.

What are the biggest supermarket trends for 2027–2029?
European grocery retail is entering a period of modest volume growth, persistent margin pressure and accelerating investment in data, AI and technology. McKinsey's State of Grocery Europe 2026 reports that European grocery sales grew 3.4% in 2025, but volume increased only 0.6%, while EBIT margins remained under pressure at 2.8%. At the same time, 47% of grocery CEOs identified AI and automation as one of their top three priorities.
This changes the strategic question for supermarket executives.
It is no longer simply: “Which supermarket technology should we invest in?”
It is: “Which combination of technology, format, design and customer experience will create the strongest commercial return from each location?”
The six trends below are therefore not isolated developments. They are interconnected components of a new supermarket operating and design model.
The supermarket trends at a glance
Invisible AI: Predictive rather than reactive operations. The commercial opportunity is to improve availability, increase efficiency and reduce waste. Key measures include availability, waste and forecast accuracy.
Hyper-local formats: More flexible rather than standardised stores. The commercial opportunity is to improve relevance to each catchment and increase sales productivity. Key measures include sales per square metre, basket size and frequency.
Experience-led design: Stores become destinations rather than purely transactional spaces. The commercial opportunity is to increase discovery, engagement and basket size. Key measures include dwell time, conversion and basket size.
Fresh-food platforms: Food becomes theatre and service. The commercial opportunity is to increase visit frequency and higher-value shopping missions. Key measures include fresh-food sales, food-to-go revenue and margin.
Phygital retail: Digital and physical shopping become one connected journey. The commercial opportunity is to improve convenience and customer loyalty. Key measures include conversion, loyalty and cost-to-serve.
ROIC-led investment: Supermarket trends are measured by their financial return. The commercial opportunity is to allocate capital more effectively and improve investment performance. Key measures include payback, incremental sales and ROIC.
The important point is that no single trend will define the future supermarket.
The competitive advantage will come from how effectively retailers connect them.

1. Invisible AI becomes supermarket infrastructure
One of the most important supermarket technology trends for 2027–2029 will be the movement of AI from visible innovation to invisible infrastructure.
But AI may increasingly determine:
- what products are stocked;
- how much inventory is required;
- when replenishment occurs;
- how space is allocated;
- which promotions are activated;
- how prices respond to demand;
- where fresh-food capacity is concentrated;
- how online and in-store inventory is coordinated;
- and which customer propositions work in each catchment.
McKinsey's 2026 grocery research shows that AI has moved firmly onto the CEO agenda, but also highlights a critical problem: 70% of grocery CEOs report no measurable EBIT impact from AI so far, or say it is too early to tell.
That creates an important strategic lesson. AI investment does not automatically create AI value.
The retailers most likely to benefit will be those that connect AI to clearly defined commercial problems.
Where AI can create supermarket value
- Demand forecasting can improve availability while reducing excess stock.
- Predictive replenishment can improve shelf availability and labour productivity.
- Assortment optimisation can identify which SKUs are genuinely relevant to individual locations.
- Pricing and promotion analytics can improve margin and reduce ineffective discounting.
- Loyalty data can enable more relevant offers and recommendations.
- Space optimisation can connect customer behaviour to category allocation.
- Predictive maintenance can reduce operational disruption.
The next step is to connect these capabilities to supermarket format strategy.
A high-density urban store may require an entirely different AI-driven operating model from a suburban weekly-shop destination.
AI therefore becomes more than an operational tool.
It becomes a mechanism for deciding what the store should be.
The commercial test
Every AI investment should answer: Which measurable customer, revenue, productivity or cost problem will this technology improve?
This prevents AI from becoming a technology programme disconnected from supermarket economics.
Internal-link opportunity: This pillar should link to specialist CampbellRigg content on AI-powered supermarket transformation rather than reproducing an entire AI strategy within this article.

2. Hyper-local supermarket formats replace one-size-fits-all
The second major supermarket trend is the move from standardised formats towards hyper-local supermarket strategy.
Traditional supermarket economics rewarded replication.
One format could be rolled out across hundreds of locations, creating purchasing, operating and branding efficiencies.
But customers do not behave identically across every catchment.
An urban commuter location has different needs from a suburban family supermarket.
A residential neighbourhood has different demand from a transport hub.
A destination store has different economics from a convenience-led local store.
The result is a strategic shift: From “How do we replicate this supermarket?” to “What supermarket should exist in this location?”
Deloitte has described the wider retail shift as moving from “mass to micro”, with increasingly differentiated consumer needs driving more personalised propositions.
The hyper-local supermarket equation
Catchment intelligence → customer mission → assortment → format → design → experience → commercial performance
This does not mean abandoning scale.
It means using scale more intelligently.
A retailer can retain a consistent brand identity while adapting:
- store size;
- SKU depth;
- fresh-food allocation;
- food-to-go;
- services;
- digital functionality;
- customer navigation;
- visual merchandising;
- hospitality;
- local product ranges;
- and promotional messaging.
The result is a portfolio of purposeful supermarket formats, rather than a network of identical boxes.
What hyper-localisation should achieve
A hyper-local format should be able to answer:
Who is the customer?
Why are they visiting?
What do they need?
What will make them choose this store?
Which products and services deserve the most space?
What experience can this location deliver better than digital or competitors?
The strategic benefit is better alignment between space, customer demand and capital investment.

3. Experience-led supermarket design becomes a commercial strategy
Experience-led supermarket design is often misunderstood as making stores look more attractive.
That is too narrow. The real opportunity is to use architecture, interiors, visual merchandising, food theatre, service and technology to create additional commercial value.
Deloitte's 2025 retail outlook found that more than one-third of executives cited enhancing the in-store experience as a top growth opportunity, while nearly half planned moderate-to-significant investment in physical-store remodels or new locations.
The store therefore remains commercially important even as online grocery expands.
The question is what the physical environment does that digital channels cannot.
The future supermarket experience should combine
Functional efficiency
Customers can find products quickly, navigate easily and complete transactions with minimal friction.
Discovery
The store provides inspiration, new products, seasonal propositions and reasons to explore.
Service
Employees, specialist counters and expert advice add value that algorithms cannot fully replicate.
Sensory experience
Fresh food, preparation, cooking, aroma and visual merchandising make the physical store distinctive.
Community
Local relevance and social spaces can create stronger emotional connections.
Digital assistance
Technology provides information, navigation, personalisation and convenience without dominating the environment.
This creates a useful strategic principle: Digital intelligence removes friction. Physical experience creates differentiation. The objective is not maximum dwell time. It is maximum value from the customer mission.
A faster journey may be commercially superior for a convenience customer. A longer, discovery-led journey may be more valuable for a destination shopper.
Experience must therefore be designed around customer mission and commercial purpose.

4. Fresh food, food-to-go and hospitality become growth platforms
Fresh food is becoming one of the most important bridges between supermarket retail and experience.
McKinsey identifies fresh foods, convenience and food-to-go among the growth pockets in European grocery. Its 2026 research also notes that retailers are rethinking layouts to make foodservice and ready-to-eat options more visible and accessible.
This matters because fresh food combines several attributes that digital grocery struggles to replicate:
- visual theatre;
- aroma;
- freshness;
- service;
- preparation;
- provenance;
- expertise;
- immediate consumption;
- and social interaction.
Bakery, produce, prepared foods, food-to-go, coffee, specialist counters and open kitchens can therefore become destinations within the supermarket.
Fresh food can perform four strategic roles
1. Brand
Fresh food communicates quality and positioning.
2. Experience
Preparation and presentation create theatre.
3. Frequency
Ready-to-eat and food-to-go propositions can create more frequent visits.
4. Basket growth
Fresh and prepared-food missions can introduce additional purchases beyond the planned grocery list.
The opportunity is therefore not simply to allocate more space to fresh food.
It is to design fresh food as an integrated customer experience and commercial platform.

5. Phygital supermarkets connect digital and physical retail
The distinction between online and offline grocery is becoming less useful.
The future customer journey may look like: AI discovery → personalised recommendation → digital comparison → store visit → physical experience → loyalty offer → purchase → replenishment
The store is one component within a wider phygital supermarket ecosystem.
FMI and NIQ reported that 92% of food retailers surveyed were using technology, including AI, to personalise or customise shopping or marketing experiences online and in-store.
Meanwhile, agentic AI is beginning to change how grocery shopping could be initiated and completed. FMI describes AI agents as potentially moving grocery shopping towards automated systems that can plan meals, manage budgets and place orders on behalf of consumers.
That creates an important future challenge for physical retail.
If an AI agent increasingly determines what a customer buys, the physical supermarket needs to provide compelling reasons for the customer to experience the brand and products.
Phygital supermarket design can integrate
- personalised offers;
- digital navigation;
- loyalty platforms;
- predictive availability;
- frictionless checkout;
- click-and-collect;
- interactive information;
- digital signage;
- AI-powered customer service;
- omnichannel fulfilment;
- connected-home and lifestyle experiences.
But technology should not become the visual identity of the store.
The strongest phygital supermarket environments will make digital functionality feel natural, useful and brand-consistent.
The objective is one connected customer experience rather than a collection of technology installations.

6. Supermarket productivity and ROIC become the critical performance measures
This may be the most commercially important supermarket trend of 2027–2029.
Technology, branding, architecture and experience are increasingly capital-intensive.
Retailers therefore need to demonstrate what those investments actually deliver.
Sales remain essential.
But sales alone do not provide a sufficient measure of supermarket performance.
A sophisticated supermarket ROIC framework should connect investment to:
Technology performance
- Forecast accuracy
- Availability
- Waste
- Replenishment efficiency
- Labour productivity
- Fulfilment cost
Store performance
- Sales per square metre
- Gross margin per square metre
- Space productivity
- Conversion
- Category performance
- Basket value
Customer performance
- Visit frequency
- Loyalty
- Customer retention
- Engagement
- Food-to-go penetration
- Omnichannel participation
Investment performance
- Capital expenditure
- Incremental sales
- Incremental margin
- Cost savings
- Payback period
- ROIC
The central question should always be: What measurable commercial return will this investment generate?
McKinsey's 2026 grocery research reinforces why this discipline matters: grocery CEOs continue to face structural cost and margin pressure, while many retailers have yet to translate AI investment into measurable EBIT impact.
The implication is clear: The future supermarket cannot afford technology, design or experience programmes that are disconnected from economics.
What Tesco, Whole Foods, and Monetka reveal about the future supermarket
The most useful supermarket case studies are not necessarily those with the most technology.
They are the retailers that demonstrate a clear relationship between customer proposition, format, experience and commercial strategy.
Tesco: scale through differentiated formats
Tesco demonstrates how a large supermarket group can combine scale with local relevance through a diversified store-format strategy. Its Extra, Superstore, Metro and Express formats serve different locations, customer needs and shopping missions, rather than relying on a single standardised model.
This flexibility allows Tesco to adapt store size, range and proposition to local demand while maintaining the efficiencies of a large-scale operation. Its value-to-premium positioning, including Aldi Price Match, Low Everyday Prices and Tesco Finest, further broadens its appeal across different customer segments and budgets.
Commercial lesson: Scale creates efficiency; differentiated formats create relevance and customer value.
Tesco: Scale Through Differentiated Formats
Tesco demonstrates how a large supermarket group can use different store formats to serve varied locations, customers and shopping missions.
Its Extra, Superstore, Metro and Express formats range from large destination stores to smaller convenience-led locations. This flexible format architecture enables Tesco to adapt store size, assortment and proposition to local demand rather than applying one standard model everywhere.
Tesco also balances value and quality through propositions such as Aldi Price Match, Low Everyday Prices and the premium Tesco Finest range, appealing to customers across different budgets and shopping needs.
Commercial lesson: Use scale for efficiency, but use format flexibility to remain relevant to local customers.

Whole Foods Market: fresh food as brand experience
Whole Foods Market operates two main active store formats. The traditional full-size supermarket of 40,000 square feet offering full departments of organic produce, meat, seafood, bakery, and wellness items and the newer, compact urban quick-shop format. Whole Foods Market Daily Shop: ranging from roughly 3,300 to 14,000 square feet designed for high-density city neighbourhoods with grab-and-go meals, essentials, and core grocery selections.
Whole Foods Market demonstrates how fresh food, prepared food, quality communication and specialist propositions can turn the supermarket into part of the product experience. Its approach makes the physical store more than a place to purchase groceries, creating a stronger sense of discovery, quality and expertise.
This experience-led model is increasingly important as routine grocery shopping shifts online. Fresh food, food-to-go, specialist ranges and visible product quality give customers compelling reasons to visit physical stores and spend more time in them.
Commercial lesson: Fresh food can function simultaneously as product, experience, brand and destination.

Monetka: Scalable Identity and Format Consistency
Monetka, the Russian convenience retailer operates over 2,120 stores across Russia, demonstrates how a scalable brand and store-format system can create consistency across a multi-site supermarket network. A coherent identity, layout principles and customer experience help maintain brand recognition while allowing individual stores to respond to different locations and local conditions.
The strategic challenge is to balance consistency with localisation. Rather than applying an identical store model everywhere, supermarket operators can adapt formats and assortments within a clearly defined brand architecture.
Commercial lesson: Localisation works best when it operates within a coherent brand and format architecture.

From bigger supermarkets to better-matched supermarkets
The future of supermarket retail is not simply smaller stores.
It is better-matched stores.
Large destination supermarkets will continue to serve weekly and family shopping missions.
Smaller urban stores can serve convenience and immediate-consumption needs.
Neighbourhood supermarkets can emphasise fresh food, local relevance and community.
Transport and employment hubs can prioritise food-to-go and speed.
Experience-led destination stores can combine grocery, foodservice, hospitality and discovery.
The winning retailer will therefore be able to determine:
- Which format?
- For which customer?
- In which location?
- With which assortment?
- At what investment level?
- Generating what return?
This is where AI and customer intelligence become strategically important.
Data can increasingly help retailers decide where each format belongs and how each store should perform.

The Supermarket 2027–2029 Investment Framework
Before approving a new supermarket, refurbishment, technology programme or format transformation, retail leaders should be able to answer six questions.
- Who is the customer?
What are the dominant demographics, behaviours, shopping missions and unmet needs within the catchment? - What should the format do?
Should the store prioritise convenience, weekly shopping, fresh food, food-to-go, discovery, hospitality, fulfilment or a combination? - What should technology improve?
Where can AI, predictive analytics, loyalty data and digital services improve availability, relevance, productivity or convenience? - What should the physical experience deliver?
Which elements of architecture, interiors, visual merchandising, food theatre and service provide value that digital channels cannot replicate? - How will performance be measured?
Which KPIs will demonstrate improvement in sales, margin, productivity, loyalty, efficiency or customer value? - What is the ROIC case?
What incremental revenue, margin improvement, cost saving or productivity gain is required to justify the investment?
This framework changes the strategic conversation from: “What will the future supermarket look like?” to: “What supermarket model will produce the strongest commercial return for this customer, location and investment?”
That is the more important question.

How Supermarket Leaders Can Turn Trends into ROIC
The six trends should not be managed as separate programmes. They should work together as one integrated commercial system, linking customer insight, technology, format strategy, branding, design and performance.
- It starts with shopper insight, identifying customer missions, behaviours and local demand.
- AI and data then turn this information into predictive intelligence that can guide decisions.
- This intelligence informs format strategy, determining what each store should be and the role it should play.
- Brand architecture provides consistency across the network while allowing local relevance.
- Store design then translates the strategy into architecture, interiors, navigation, merchandising and customer experience.
- Phygital integration connects physical and digital journeys, making the overall customer experience more seamless.
Finally, performance measurement tracks sales, productivity, loyalty, efficiency and customer value. These measures determine whether the investment is delivering sustainable ROIC.
The real opportunity in supermarket transformation is therefore not technology for technology’s sake, experience for experience’s sake, or design for design’s sake.
It is the integration of all three around measurable commercial performance.
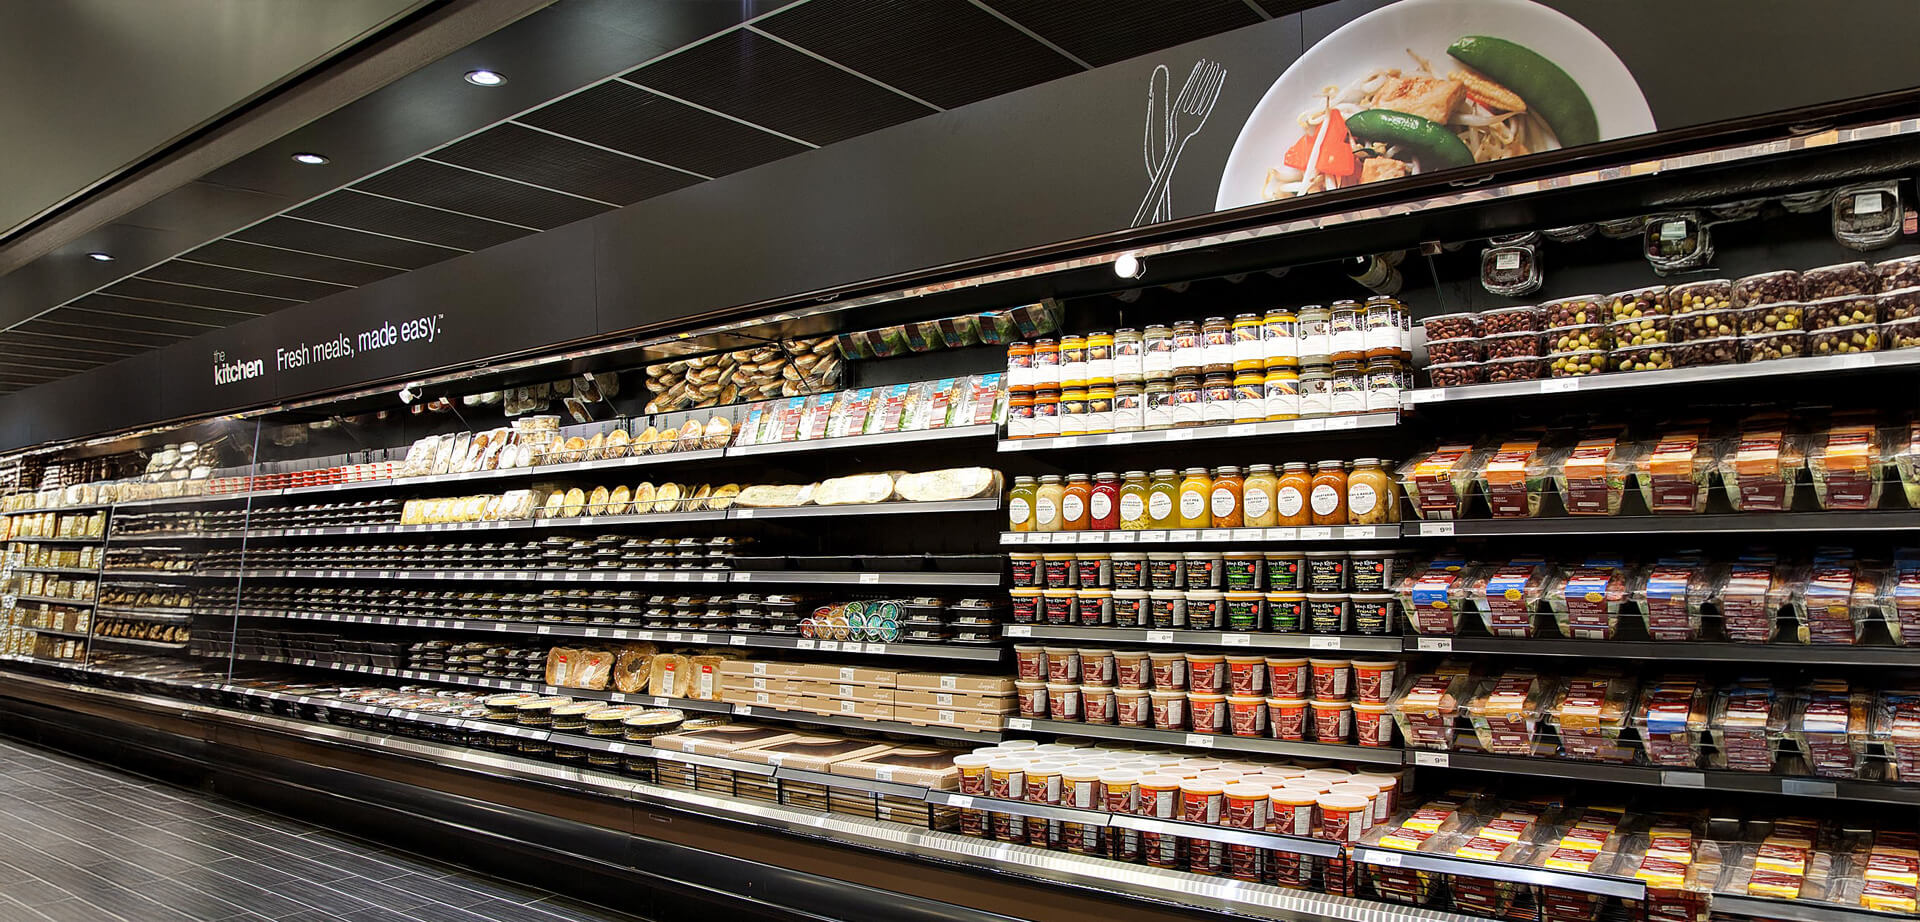
Below: CampbellRigg supports Monetka with scalable store design, format strategy, and brand alignment across 2120+ locations, improving local relevance, operational efficiency, and performance per square metre.

CampbellRigg: supermarket strategy, design and commercial transformation
CampbellRigg helps supermarket and grocery retailers translate shopper insight, brand strategy, technology and format planning into commercially productive retail environments.
The approach connects:
- Supermarket strategy
- Format planning
- Brand architecture
- Retail branding
- Architecture
- Interior design
- Visual merchandising
- Customer experience
- Phygital retail
- Technology integration
- Performance-led store transformation
The objective is not simply to create a more attractive supermarket.
It is to create a better-matched, more relevant and more productive retail format.
For supermarket leaders planning new stores, refurbishments, format transformation or brand repositioning, the strategic priority is clear:
Turn supermarket trends into scalable formats, stronger customer experiences and measurable commercial performance.

Planning a supermarket transformation?
CampbellRigg can help connect customer insight, format strategy, branding, architecture, interior design, technology and experience into one commercially focused supermarket proposition.
Discuss your supermarket strategy, format transformation or store design programme with CampbellRigg.


Schedule your consultation today and receive a free quote.
Cost-Effective Excellence:
Our pricing structure is highly competitive, offering exceptional value without compromising on quality or creativity.
Rapid Execution:
We move fast. From concept to implementation, our agile team ensures your project is delivered on time and to the highest standards.
Multidisciplinary Expertise:
Our team brings together seasoned brand strategists, architects, interior designers, and graphic designers, collaborating to create seamless, end-to-end brand environments.
Global Reach, Local Insight:
With successful projects delivered across Europe, the Middle East, and Asia, we combine international experience with local market understanding.
Scalable Project Delivery:
Whether it's a flagship hypermarket store, a metropolitan city supermarket or convenience store, we manage and execute projects of all sizes, efficiently and effectively.
Proven Track Record:
Our designs evolve branch networks from purely transactional spaces into experiential, relationship-focused brand environments, enhancing engagement, elevating customer experience, and driving tangible business results.
Full-Service Creative Agency:
From rebranding and marketing campaigns to spatial design and rollout, we provide an integrated service tailored to your goals.